Some of us like wine tasting with our spouses. Some of us enjoy kayaking. But hardly any of us love a good couples' chat about finances. In fact, a Wells Fargo survey found that for Americans, money is the No. 1 most difficult topic to discuss -- even harder than death, politics, or religion. Yet a TD Bank survey found 90% of couples who say they are in a happy relationship talk about money once a month, whereas 68% of unhappy couples say they discuss it less often.
Clearly talking about money is part of a healthy relationship -- so why don't more couples discuss their dollars and cents? The answer is complicated. Gender differences have a little to do with it; the Wells Fargo survey found that half of the women who responded said it was difficult to talk with others about personal finances, versus 38% of men.
Debt is a factor, too. A Ramsey Solutions survey found that the more debt a couple had, the more likely they were to fight. Not talking about credit-card debt can also lead to sneaky behavior; in a separate study, 32% of respondents said they've hidden their credit card debt from their significant others. That can't be good for a marriage.
Money is a complicated topic, and we understand the impulse to avoid it rather than face a potential fight. But happy couples do talk about the family finances more regularly than unhappy couples do. Reaching the same page about this sensitive topic is worth the investment, so here are six steps to talking with your spouse about money without ending up yelling at each other (we hope).
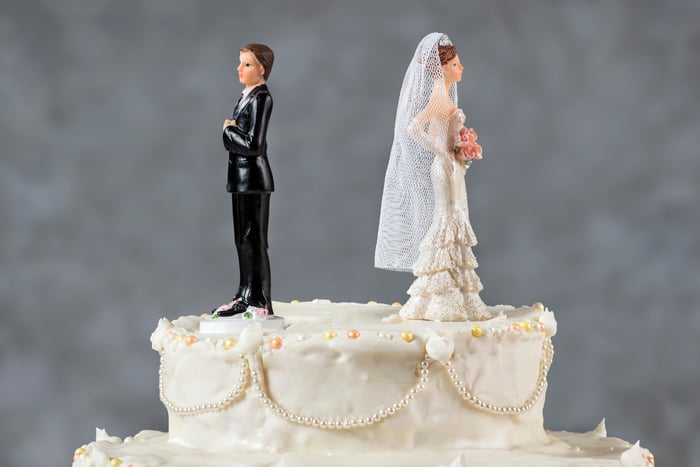
Don't let difficult conversations about money get between you and a happy marriage. Source: Getty Images.
1. Set the stageWith any hefty topic, it's best to dig in when both partners feel ready. No one likes to talk shop when they come home from a long day at work, tired and hungry. Some suggest setting and preparing for a "money date" -- a night earmarked for the discussion of your finances, free from the distractions of TV, kids, cell phones, and the like. Some may want to get out of the house and make this a true date night, while others may find it easier at home. Either way, I suggest opening a bottle of red wine.
2. Ease into the conversationIf you anticipate that the discussion might get contentious, Trent Hamm from the Simple Dollar money blog suggests admitting faults first. This is a good way to acknowledge that none of us is perfect; it's like saying, "It's not you, it's me." If you feel your spouse is spending too much money, take a look at the budget over the past few months -- there may be things you splurged on as well. Admit that you have your own flaws, and understand that everyone has a different relationship with money, one that comes from their individual background and has been forged over many years. As with any important topic worth discussing, when it comes to money, it's best to be patient.
3. Find commonalityA difficult conversation will go more smoothly if you can find common ground. Start off by posing questions; asking "When do you want to retire?" "Where should we live in retirement?" or "Where will the kids go to college?" will help get you both thinking about the same things. Try to get specific with your answers: "I want to retire in 15 years," "I think the kids should go to public college instead of private." This will help make the goals more realistic. Finally, write the goals down so you can both reference them at your next money date.
4. Look at the numbers -- but don't point fingersIt helps if you have prepared a balance sheet and can both look it over. This is a great next step, as it ensures both spouses are aware of the complete family picture. Credit-card balances, mortgage debt, car loans, student loans, investment accounts, and college accounts should all be listed and put out in the open for both partners to see.
Be careful not to judge or make comments if, for instance, one spouse has all the debt in their name. This will quickly shut down the conversation. Instead, have another glass of wine and talk about the good things you've accomplished so far, like how much you have saved or the progress you are making toward paying down a debt.
5. Start planningNow that the numbers are out in the open and the goals are clearly articulated, it's time to have some fun and start planning! Goals should be shared, so it's best to talk in terms of "we," not "you." If one person has student debt to pay back, the question is "How can we pay off the debt faster?" or "Where can we save in other places to help pay down the loan?" Talking in terms of "we" makes it a team venture, and there's greater buy-in when both partners feel that they are in it together.
There are several free financial calculators online that can help you get an idea of how much to save for a specific goal and show how paying down debt faster saves you money.
6. Set another dateAssuming you both survived the first money date unscathed and the bottle of red is empty, it's now time to schedule the next meeting. I try to do this once a quarter with my spouse. If you're just having this conversation for the first time, then maybe try once a month till you gain some traction. I find reviewing the balance sheet is an extremely useful tool that helps guide the conversation. It's also good to keep it light and recognize that however daunting any goal may seem, it all starts with communication.
Money shouldn't be a taboo topic for couples. It's too important not to discuss. If you approach it the right way -- by not judging, setting common goals, talking in terms of "we," and having regular conversations over time -- talking about money may get easier and lead to a more enriching marriage, in more ways than one. I'll drink to that.

